 Posted by
5 Important Things to Check Before Porting Your Health Insurance Policy
Planning to Switch Your Health Insurance Company? Read These 5 Important Points Before You Decide.
Have you ever felt that your existing health insurance policy is becoming expensive, or that another insurance company is offering better benefits for a lower premium?
Many people think about changing their health insurance company for these reasons. Some may not be happy with the cashless hospital network, while others may have concerns about claim services, coverage restrictions or rising renewal premiums.
This is where health insurance portability can help. It allows you to shift your existing health insurance policy to another insurance company while retaining eligible continuity benefits, subject to applicable rules.
However, porting a health insurance policy is not a decision you should take in a hurry. Before switching, take some time to understand what you are gaining and what you might be giving up.
If you are planning to port your health insurance policy in Bangalore, here are five important things worth checking.
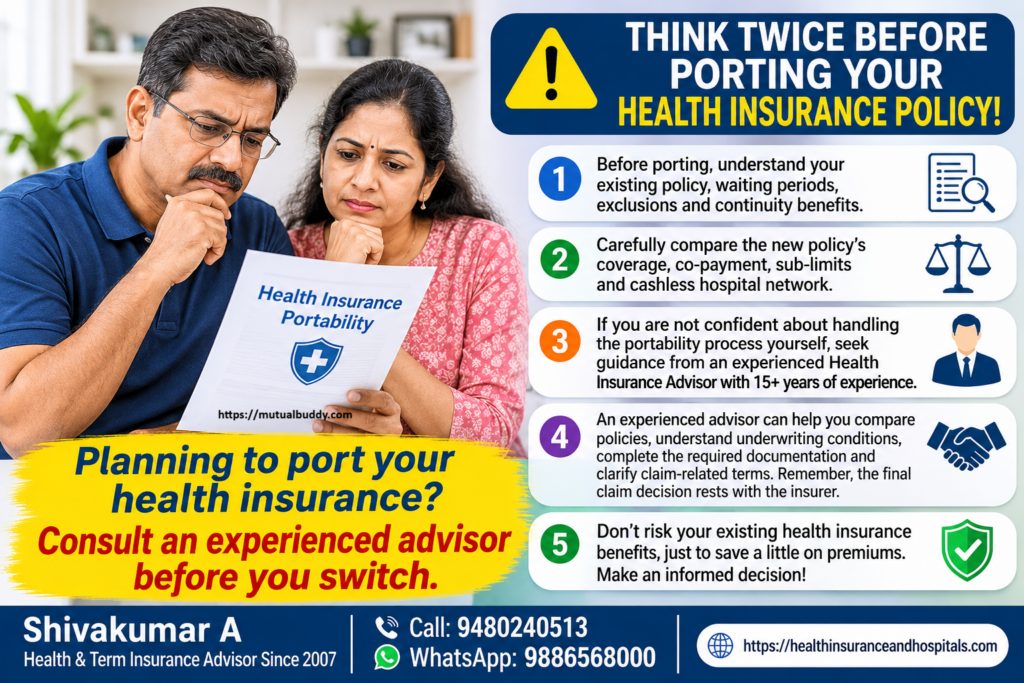
1. Understand Your Existing Waiting Period Benefits
This is probably the first thing you should look at before porting your policy.
Suppose you have been maintaining a health insurance policy for the last three years. During this period, you may have already completed the waiting period for certain illnesses or pre-existing diseases.
When you move to another insurance company, you may be eligible to carry forward the waiting period credit already earned under your existing policy.
Before proceeding, check:
- How much waiting period have you already completed?
- What is the waiting period for your pre-existing diseases?
- Have you completed the specific disease waiting periods?
- Are there any additional waiting periods for an increased sum insured?
For example, if your existing policy has a three-year waiting period for a particular pre-existing disease and you have already completed two years, the eligible two-year credit can be considered by the new insurer.
Remember, continuity benefits are subject to applicable portability rules and eligible coverage limits. Any additional sum insured may have a fresh waiting period.
Do not assume that everything will automatically transfer. Check the new insurer’s terms before making a decision.
2. Don’t Choose a Policy Just Because the Premium Is Lower
A lower premium can certainly look attractive. But is the new policy actually better than the one you already have?
This is where many policyholders make mistakes. They compare only the premium and overlook important coverage conditions.
Before porting, compare the following:
- Sum insured offered by the new policy.
- Room rent and ICU limits.
- Co-payment and deductible conditions.
- Disease-wise sub-limits.
- Restoration benefits.
- No Claim Bonus (NCB).
- Coverage for modern medical treatments.
- Pre- and post-hospitalisation expenses.
Also, take time to read the exclusions and special conditions.
A policy with a slightly higher premium but fewer restrictions may be more useful when you actually need hospital treatment.
My suggestion is simple: compare the overall benefits, not just the price you pay every year.
3. Check Whether Your Preferred Hospitals Are in the New Insurer’s Network
For people living in Bangalore, hospital network availability can make a real difference.
You may have a few preferred hospitals close to your home or workplace. Before changing your insurance company, check whether those hospitals are part of the new insurer’s cashless network.
For example, if you live in Jayanagar, JP Nagar, Whitefield, Electronic City, Marathahalli, Indiranagar or Bannerghatta Road, check the hospital options available in and around your area.
Don’t simply rely on the hospital list shown in an advertisement or on a third-party website.
Contact the new insurance company or verify directly with the hospital to confirm its current cashless arrangements.
Also remember that cashless treatment is subject to policy conditions and insurer authorisation.
Having a good sum insured is important, but knowing where you can use your policy is equally important.
4. Be Honest About Your Medical History
This is one area where you should never take shortcuts.
When applying for health insurance portability, disclose your complete medical history, even if you have already shared the same information with your existing insurance company.
Make sure you mention:
- Diabetes or high blood pressure.
- Heart-related problems.
- Thyroid conditions.
- Previous surgeries.
- Ongoing medical treatment.
- Regular medications.
- Previous hospitalisation and insurance claims.
Sometimes people feel that mentioning an existing health condition may affect their chances of getting a new policy. Because of this, they may avoid sharing certain details.
Please don’t do that.
The new insurance company may ask for medical reports, previous policy documents or medical tests before making its underwriting decision.
If you have diabetes, cardiac problems or other pre-existing diseases, carefully understand the new insurer’s decision, including any exclusions, additional conditions or premium loading.
Proper disclosure at the time of application is important to avoid unnecessary complications during future claims.
5. Don’t Cancel Your Existing Policy Until the New Policy Is Confirmed
This is a very important point.
Some policyholders assume that submitting a portability application means their new policy is guaranteed. That is not correct.
The new insurance company will review your application and may ask for additional documents or medical tests before deciding whether to accept the proposal.
Here is what you should do:
- Start the portability process preferably 30–60 days before your existing policy renewal date.
- Submit the required portability and proposal forms.
- Provide your existing policy details and medical history.
- Complete medical tests or submit reports if requested.
- Carefully review the new premium, coverage, exclusions and underwriting conditions.
- Proceed only after the new policy is issued and continuity arrangements are confirmed.
Never allow your existing policy to lapse simply because you have applied for portability.
Maintaining uninterrupted health insurance coverage is important, especially if you have already completed several waiting periods.
Is Switching Your Health Insurance Company Always the Right Decision?
Not necessarily.
Sometimes, continuing with your existing insurance company may be a better option.
If you have maintained your policy for many years, completed important waiting periods and are satisfied with the coverage and hospital network, think carefully before switching.
On the other hand, if you are facing genuine coverage limitations, unsuitable policy conditions or other concerns, exploring portability may make sense.
Every person’s situation is different. Your age, medical history, previous claims, existing coverage and future healthcare requirements should all be considered before taking a decision.
Don’t port your health insurance policy just because someone offers you a cheaper premium. First understand the benefits, limitations and conditions of the new policy.
Need Help Before Porting Your Health Insurance Policy in Bangalore?
Choosing a health insurance policy is not simply about selecting an insurance company. It is about understanding the coverage and knowing whether the policy will meet your healthcare needs when you need it most.
Shivakumar A
Health & Term Insurance Advisor Since 2007,
Call / WhatsApp: 9886568000
Alternate Contact: 9480240513
Website: https://healthinsuranceandhospitals.com
Personal guidance on:
- Individual Health Insurance
- Family Floater Health Insurance
- Senior Citizen Health Insurance
- Parents’ Health Insurance
- Health Insurance for Diabetic Patients
- Health Insurance for Cardiac Patients
- Health Insurance Portability
- Policy Review and Claim-Related Guidance
My approach is simple: understand your existing policy, compare the available options and help you make an informed decision without unnecessary pressure.
Your health insurance should protect you when you need it most. Make sure you understand your policy before making a switch.
Disclaimer: Health insurance portability is subject to applicable IRDAI regulations, insurer underwriting and the terms and conditions of the new policy. Continuity benefits are subject to applicable rules and eligible coverage limits.