 Posted by
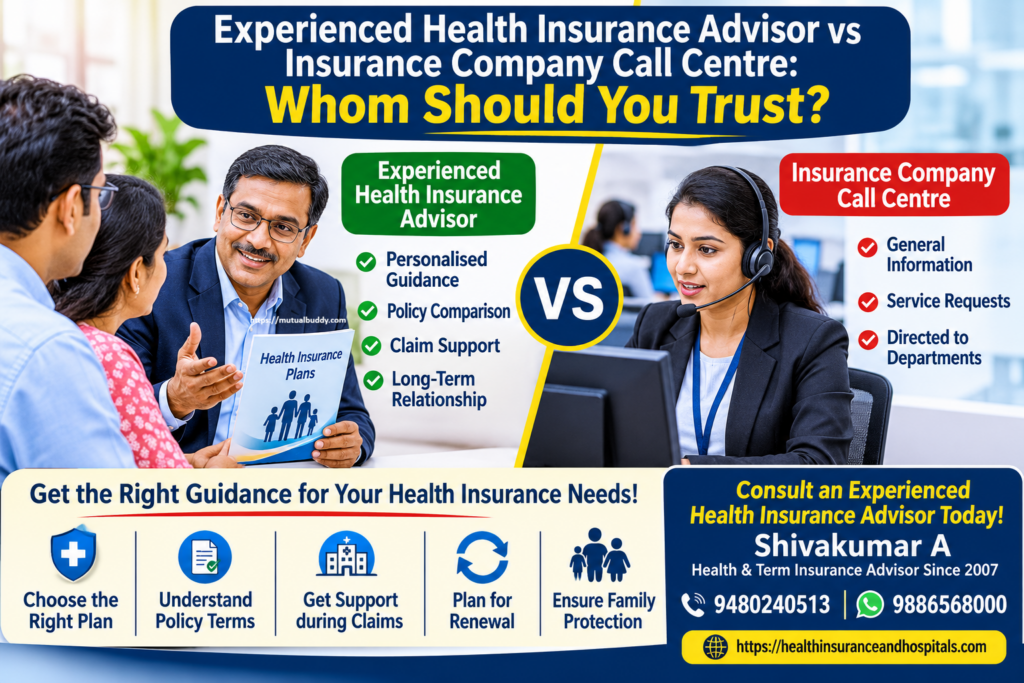
Experienced Health Insurance Advisor vs Insurance Company Call Centre: Whom Should You Trust?
Buying Health Insurance Is Easy. Getting the Right Guidance When You Need It Matters More.
Today, buying health insurance has become quite easy. You can visit an insurance company’s website, compare different plans, speak to a call centre executive or purchase a policy online within minutes.
But have you ever thought about what happens after you buy the policy?
What if you need help understanding a waiting period? What if your family member is hospitalised and you are unsure about the cashless claim process? What if you want to change your insurance company or need help during policy renewal?
At such times, having access to an experienced health insurance advisor can make a difference.
An insurance company call centre has its own importance. It can provide policy information, register service requests and direct customers to the appropriate department. However, the experience of speaking to a call centre and dealing with a personal advisor can be quite different.
Let’s understand why.
1. Someone Who Understands Your Requirements
Every family has different health insurance requirements.
A young IT professional working in Bangalore may need a different type of coverage compared to a family with school-going children or someone looking for health insurance for senior citizen parents.
When you speak to a personal health insurance advisor, you have an opportunity to discuss your family size, age, medical history, budget and future requirements.
Instead of simply looking at the premium, an experienced advisor can help you understand which policy features are important for your situation.
A call centre executive generally handles customer enquiries and explains available policy information. Personalised policy discussions may require additional assessment or support.
2. Understanding What Your Health Insurance Policy Actually Covers
Many people purchase health insurance without reading the policy conditions carefully.
They usually concentrate on the sum insured and annual premium. Unfortunately, they may overlook important details that become relevant during hospitalisation.
For example:
- Is there a room rent restriction?
- What is the waiting period for pre-existing diseases?
- Are there any disease-wise sub-limits?
- Does the policy have a co-payment condition?
- What are the permanent exclusions?
- How does the restoration benefit work?
- What hospitalisation expenses are covered?
These are not small details. They can make a significant difference when you need medical treatment.
An experienced health insurance advisor can explain these conditions in simple language and help you compare different policies before you decide.
My suggestion is simple: never purchase a health insurance policy without understanding what it covers and what it does not cover.
3. Guidance When Your Family Needs Hospitalisation
Think about a situation where your parents or spouse suddenly need hospitalisation.
At that moment, your family will be more concerned about treatment and recovery than reading insurance documents.
Naturally, questions may arise:
- How do we apply for cashless treatment?
- What documents are required?
- What happens if cashless authorisation is delayed?
- How do we proceed with reimbursement?
- Whom should we contact for claim-related queries?
A personal advisor who understands your policy can help you identify the correct process, explain documentation requirements and guide you towards the appropriate insurance company or TPA channel.
Of course, the final decision regarding claim approval and settlement rests with the insurance company.
An advisor cannot guarantee that every claim will be approved. However, having someone who can explain the process and guide you during a difficult situation can be valuable.
4. Someone to Guide You During Renewal
Health insurance is not something you purchase once and forget about.
Your requirements may change over the years. Your children grow up, your parents become older and your healthcare needs may increase.
At renewal time, you may have questions about premium increases, changes in policy benefits, additional coverage or whether your existing sum insured is sufficient.
An experienced advisor can help you review your existing policy and understand the changes before renewal.
Rather than making decisions at the last minute, it is better to review your coverage in advance.
This kind of continued relationship is one of the advantages of having a personal health insurance advisor.
5. Be Careful Before Porting Your Health Insurance Policy
Sometimes, customers decide to change their insurance company because another insurer offers a lower premium or attractive benefits.
But is switching always the right decision?
Not necessarily.
Before porting, you should check your completed waiting periods, continuity benefits, pre-existing disease coverage, exclusions, co-payment and cashless hospital network.
An experienced advisor can help you compare your existing policy with the proposed policy and understand the important differences.
Remember, you may have maintained your existing policy for several years. Don’t give up eligible benefits without understanding the consequences.
A lower premium should never be the only reason for switching your health insurance company.
6. Call Centre Support and Personal Advisor: Both Have Their Place
This is not about saying that insurance company call centres are unnecessary.
They play an important role in handling customer service enquiries, policy-related requests, official communications and claim-related processes.
Ideally, you should have both the insurer’s official support system and access to a knowledgeable advisor.
The important thing is to know whom to approach and where to get the right information when you need it.
Looking for an Experienced Health Insurance Advisor in Bangalore?
I am Shivakumar A, a Health & Term Insurance Advisor since 2007.
Over the years, I have understood that customers don’t just need a health insurance policy. They also need someone who can explain the benefits, clarify the conditions and guide them when questions arise.
My approach is straightforward.
I first try to understand your requirements, explain the available options and discuss the important policy conditions. I give customers sufficient time to understand and make their own decisions without unnecessary pressure.
Health Insurance Services:
- Individual Health Insurance
- Family Floater Health Insurance
- Senior Citizen Health Insurance
- Health Insurance for Parents
- Health Insurance for Diabetic Patients
- Health Insurance for Cardiac Patients
- Health Insurance Portability
- Policy Review and Renewal Guidance
- Hospitalisation and Claim-Related Guidance
Shivakumar A
Health & Term Insurance Advisor Since 2007
Call: 9480240513, WhatsApp: 9886568000
Website: https://healthinsuranceandhospitals.com
My belief is simple: Buying a health insurance policy should not be the end of your relationship with an advisor. You should know where to turn when you need guidance.
Before choosing a health insurance policy, ask questions, understand the conditions and make an informed decision.
Disclaimer: Insurance coverage, underwriting, cashless facilities and claim settlements are subject to the respective insurer’s policy terms, conditions and applicable regulations. An advisor cannot guarantee claim approval or settlement.